Digital payments: what they are and how they work
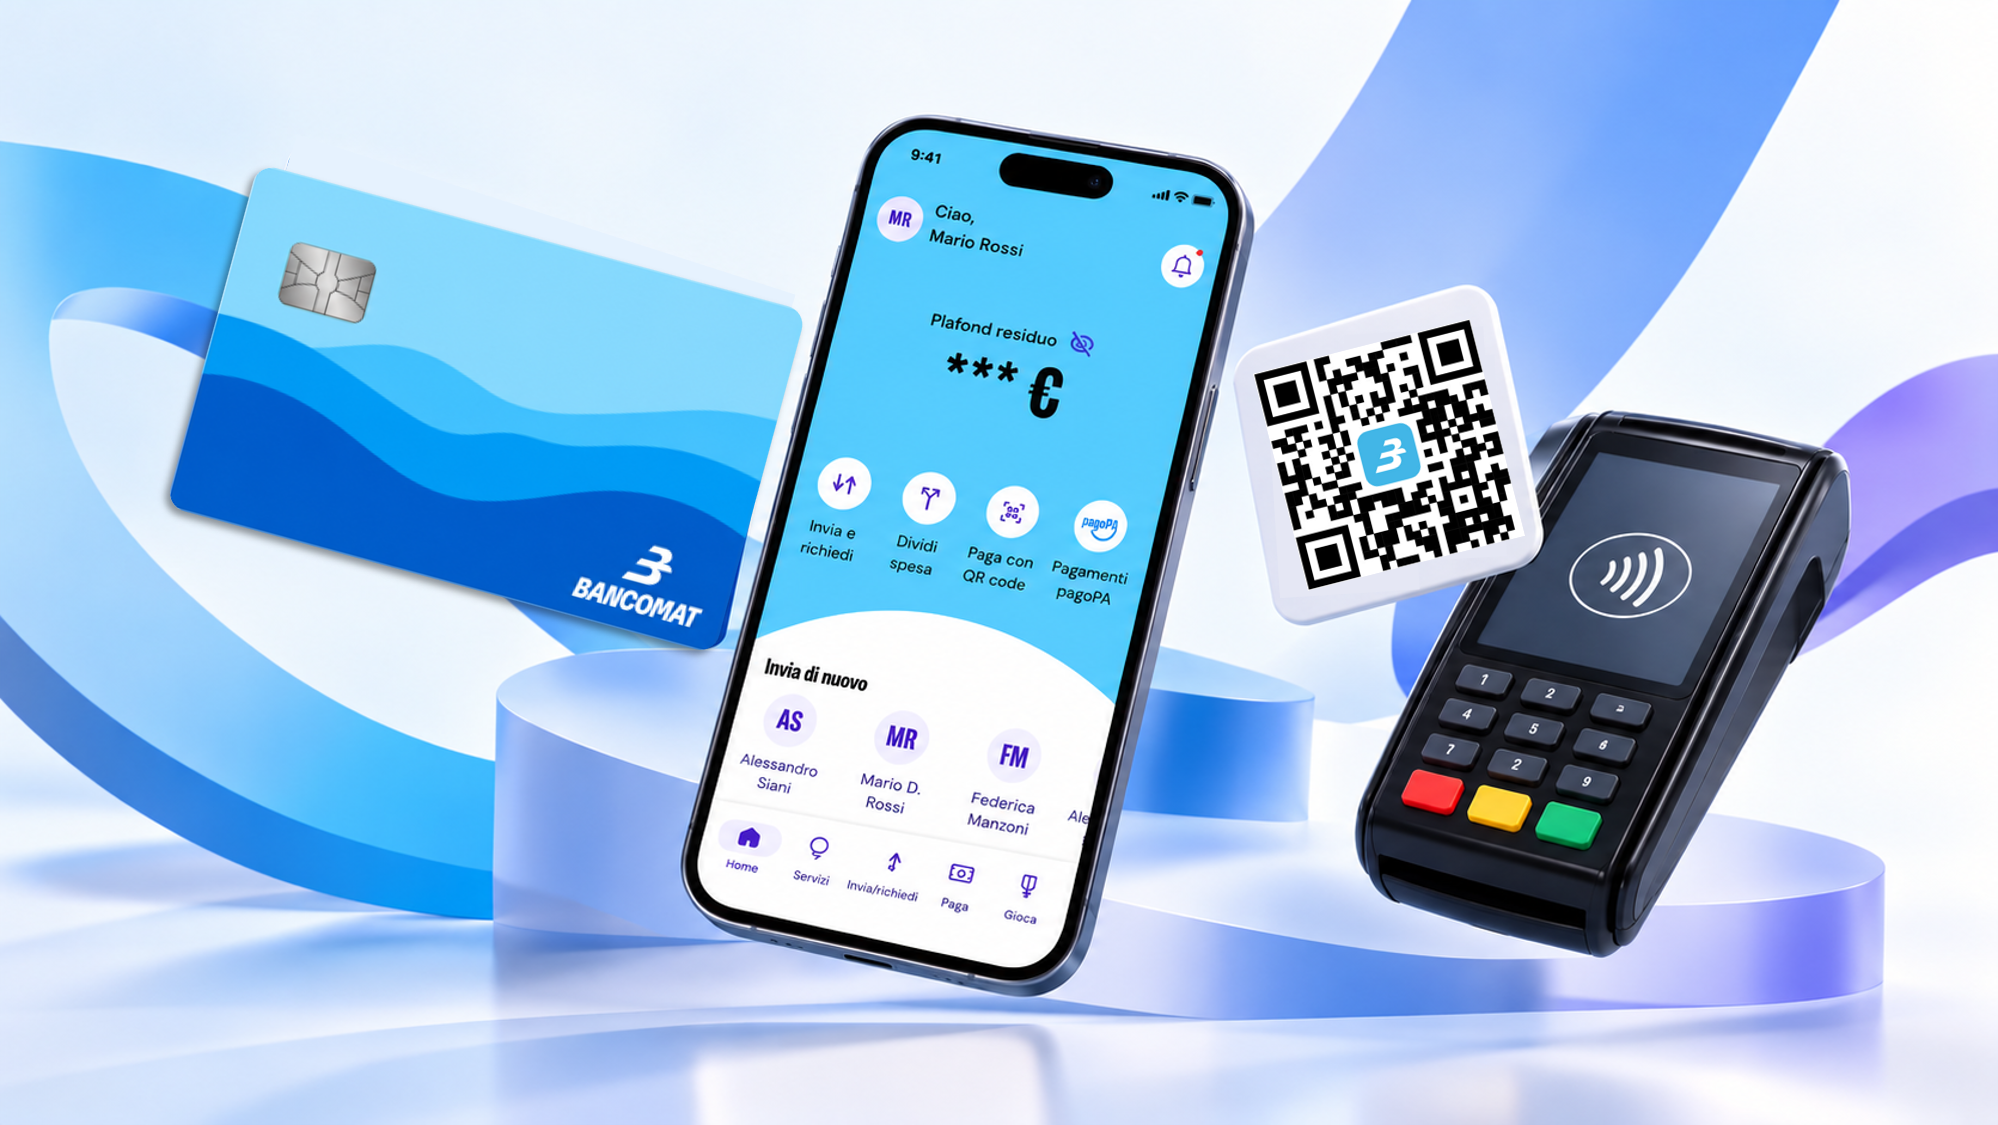
Digital payments make it possible to purchase goods and services using electronic tools, without the direct use of cash. This category includes transactions that are now very common, such as paying by card in a store, making a bank transfer through home banking, paying via a digital wallet such as Apple Pay, Samsung Wallet, Google Pay , Huawei Pay or making payments to the Italian Public Administration through pagoPA.
One service that enables various types of digital payments is BANCOMAT Pay, which links a phone number to a bank account and allows users to make online, in-store and Public Administration payments via smartphone. The service also enables peer-to-peer (P2P) money transfers.
There are different payment methods, as well as different technologies used to authorize and manage transactions. Let’s take a look at what digital payments are, the main methods involved, and how they work.
What are digital payments
Digital payments are payment transactions carried out using electronic tools and systems, without the direct exchange of cash. Consequently, this category encompasses all transactions in which the payment is initiated and managed digitally.
These transactions can take place in different contexts: in a physical store, online, through an app or via a bank account. In fact, digital payments do not necessarily require the use of a smartphone: a card used at a POS terminal or a bank transfer made through home banking are also examples of digital payments.
The category therefore includes different tools and payment methods, all of which use electronic systems to execute and manage transactions, as well as technologies and security systems designed to protect data and operations.
Digital payments: what are the main methods?
There are many digital payment methods, allowing users to make purchases using different tools depending on the context and their needs. Key examples include payment cards, bank transfers, digital wallets, and app-based payment systems.
Credit, debit, and prepaid cards
Payment cards can be used to make purchases in-store, online, and, when enabled, via contactless mode. The way the transaction amount is charged to your account depends on the type of card:
- with a debit card, the amount is debited directly from the linked bank account;
- with a credit card, the amount is charged to the bank account after the transaction date, according to the terms and timing established in the issuer’s contract;
- with a prepaid card, users can spend the funds that have previously been loaded onto the card.
Bank transfers
A bank transfer makes it possible to transfer money directly from your account to the recipient’s account and can be initiated through home banking services or banking apps.
The main distinction is between standard and instant bank transfers. In the first case, the transfer is completed according to standard banking processing times, generally within one or more business days. An instant bank transfer, on the other hand, allows funds to be transferred and made available in the recipient’s account within seconds.
Fees and conditions applied to bank transfers may vary depending on the bank and the service used.
Digital wallets
Digital wallets are applications that make it possible to digitize a payment card and use it via a smartphone, smartwatch or other compatible device. Some of the main examples include Apple Pay, Samsung Wallet, Google Pay and Huawei Pay.
App-based and QR code payments
There are systems that allow payments to be made directly via an app, for example by using a phone number or scanning a QR code.
In the case of QR code payments, scanning the code allows the system to retrieve the information required to initiate the transaction, which is then verified and confirmed through the payment service being used.
Digital payments with BANCOMAT Pay
BANCOMAT Pay allows users to make different types of digital payments directly from a smartphone by linking their phone number to their bank account. The service can be used to pay in physical stores, online and to the Italian Public Administration through pagoPA.
To pay online with BANCOMAT Pay, users simply enter the phone number associated with the service at checkout on the enabled merchant’s e-commerce website and authorize the transaction directly from the app.
Digital card payments: how they work
A digital card payment follows several main steps. When the customer initiates a payment, the data required for the transaction is securely transmitted to the systems involved, which verify the transaction and, when necessary, the user’s identity. The payment is then authorized or declined, and the outcome is communicated to both the customer and the merchant.
Different technologies and tools are involved in this process, making it possible to transmit information, verify the user’s identity and protect the data used during the transaction.
The steps of a digital card transaction
In general, a digital card transaction can be described through a number of key steps:
- the customer selects the payment method;
- the required data is transmitted through secure systems;
- when required, the system identifies or authenticates the user;
- the bank or service provider verifies the transaction;
- the payment is authorized or declined;
- the customer and the merchant receive confirmation of the outcome.
Payment authorization and the final transfer of funds do not necessarily take place at the same time. In fact, in some cases, the transaction is authorized first, while settlement of the funds is completed at a later stage.
Encryption and tokenization
Encryption is a technology that protects data while it is being transmitted, making it unreadable to unauthorized parties. When making a card payment through a digital wallet, the card information may be replaced with a digital code known as a token, which is used to complete the transaction. Tokenization therefore makes it possible to avoid using the card details directly during the payment process.
NFC and contactless payments
NFC (Near Field Communication) is a technology that allows two compatible devices to communicate when they are placed very close to each other. In contactless payments, for example, it allows a card, smartphone or smartwatch to communicate with a POS terminal simply by bringing the device close to the terminal.
QR code payments use a different technology: the code is generally scanned using a smartphone and provides access to the information required to initiate the payment.
Strong customer authentication
One of the systems used to protect digital payments is Strong Customer Authentication (SCA), which is required under European regulations to verify the identity of the person carrying out a transaction more securely.
SCA is based on the use of at least two different authentication elements, combining, for example, something the user knows, such as a PIN or password, with something the user possesses, such as a smartphone or card, or a personal characteristic, such as a fingerprint or facial recognition. PINs, passwords or biometric data may thus be used, with methods varying according to the type of payment and the service employed.
This system is part of the broader framework of European rules and standards for payment security, which the various parties involved in providing and managing payment services must observe. This common regulatory framework offers additional safeguards for users by establishing requirements and security measures designed to protect payments and data.
POS
A POS (Point of Sale) terminal is not a payment method, but a tool that allows merchants to accept digital payments.
A physical POS terminal is the device found, for example, in stores and allows merchants to accept payments using tools such as cards or digital wallets. A mobile POS is a solution designed to accept payments through portable devices, while a virtual POS allows merchants to manage payments made online.
Advantages of digital payments
Key benefits of digital payments include the ability to make transactions quickly and conveniently, including online or remotely, as well as a reduced need to use cash.
For consumers, digital transactions also allow users to track payments, monitor spending more easily and choose between different payment tools according to individual needs, all while minimizing risks associated with handling cash, such as theft or loss.
For businesses and merchants, digital payments can simplify the management of incoming payments, reduce operational tasks related to cash handling and enable the integration of payments with e-commerce platforms and management systems.
However, transaction times, costs and terms may vary depending on the payment tool and service used.
Digital payments and security
The security of digital payments depends on both the technologies used to protect data and transactions and user behavior. Measures such as encryption, tokenization, multi-factor authentication and transaction notifications help make transactions more secure.
However, it is still important to be aware of risks such as phishing, credential theft, fake websites and smartphone misuse. Therefore, users should never share PINs, passwords or OTP codes, should use official apps and websites, check the amount and recipient before confirming a payment, and regularly review their transaction history.
To learn more about the technologies, tools and best practices involved, find out more about digital payment security and how to prevent fraud.
Frequently asked questions about digital payments
Is a bank transfer a digital payment?
Yes. A bank transfer initiated through home banking or a banking app is a digital payment because the transfer of money is initiated and managed through electronic systems.
Is a POS a digital payment?
No. A POS is not a payment method, but rather the tool through which a merchant can accept a digital transaction, such as a card payment.
Can you make digital payments without a card?
Yes. It is possible to make digital payments without using a card, for example through services linked directly to a bank account, such as BANCOMAT Pay.


documents & support
Contact usPrivacy PolicyContest RulesEthics, Compliance and TransparencyTerms and conditionsStay tuned


BANCOMAT S.p.A.
Registered Office: Piazzale Luigi Sturzo 15, 00144, Roma
Offices in Milan: Piazza Vetra, 17, 20123, Milano
Tax code 04949971008 - Partita IVA 09591661005
Iscrizione al Registro delle imprese di Roma
REA n. 1210597
Share capital € 36.917.523,00 i.v.
The security of BANCOMAT Cards haas been tested by the Polytechnic University of Turin. Download technical report

Patent registered by BANCOMAT at national level
